Having considered how businesses can navigate uncertainty, the next step is understanding the market forces behind it.
For finance leaders, the advantage lies not in predicting every economic shock, but in knowing how to interpret its implications for costs, cash flow, financing and competitiveness.
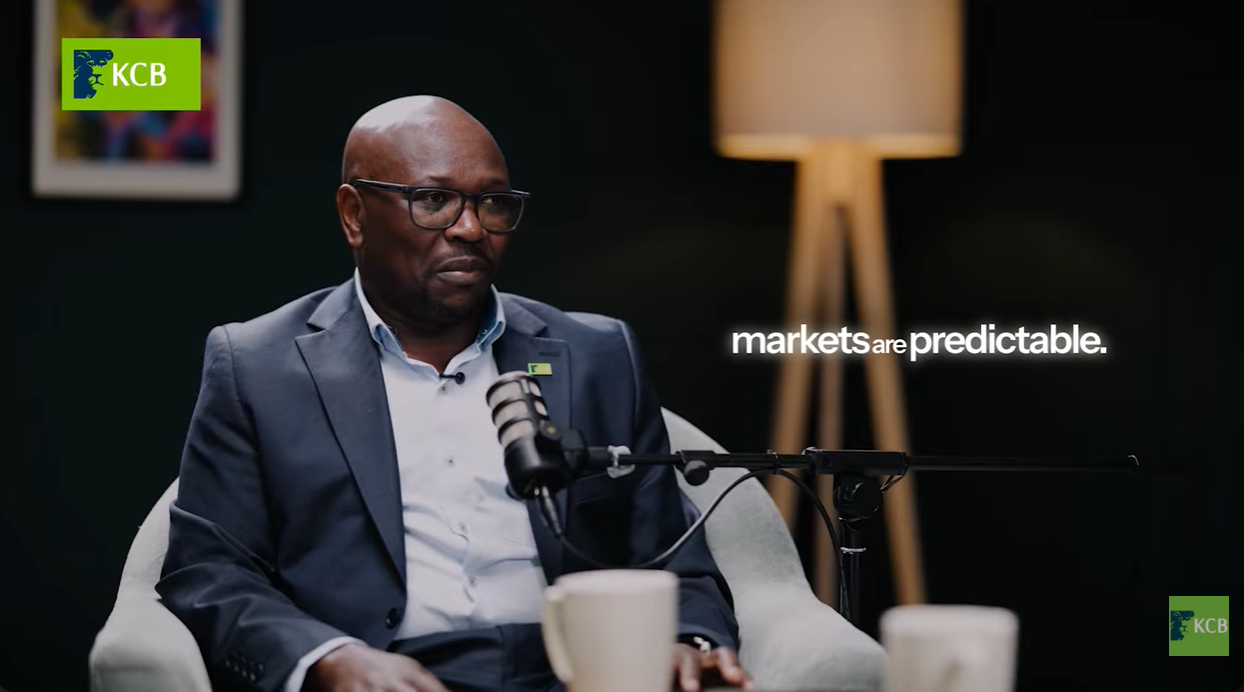
One financial myth worth challenging is that markets are predictable. In reality, economic conditions can shift quickly, changing the assumptions on which businesses base their decisions.
Resilience, therefore, depends on understanding the forces shaping the operating environment and translating that knowledge into informed financial decisions.
Consider a company preparing its annual budget. Its projections may account for expected sales, operating costs, borrowing requirements and planned investments.
Changes in energy prices, interest rates or exchange rates could quickly alter its assumptions about operating costs, borrowing and investment.
The challenge is identifying where these shifts could leave the business exposed and what adjustments may be necessary.
A movement in one indicator may appear insignificant in isolation, but its effects can extend across procurement, pricing, financing and cash flow, influencing decisions well beyond the finance department.
This is particularly evident in the interplay between inflation, interest rates, foreign exchange movements and global developments, which are closely interconnected.
Their combined effects can influence everything from procurement costs and pricing decisions to working capital requirements, debt obligations and investment returns.
Understanding these relationships helps businesses distinguish the developments that matter to their operations and make informed decisions before the financial impact becomes harder to manage.
Uncertainty Is a Business Variable, Not an Exceptional Event
Businesses operate within an economic environment shaped by forces they cannot fully control. Geopolitical tensions can disrupt supply chains and energy markets.
Inflation can increase operating expenses. Changes in monetary policy can influence borrowing costs, while exchange-rate movements can alter the cost of imports and the value of foreign-currency earnings.
These developments do not affect every business in the same way. An importer, an exporter, a manufacturer and a service provider may experience the same market movement differently, depending on their cost structures, contractual obligations and sources of revenue.
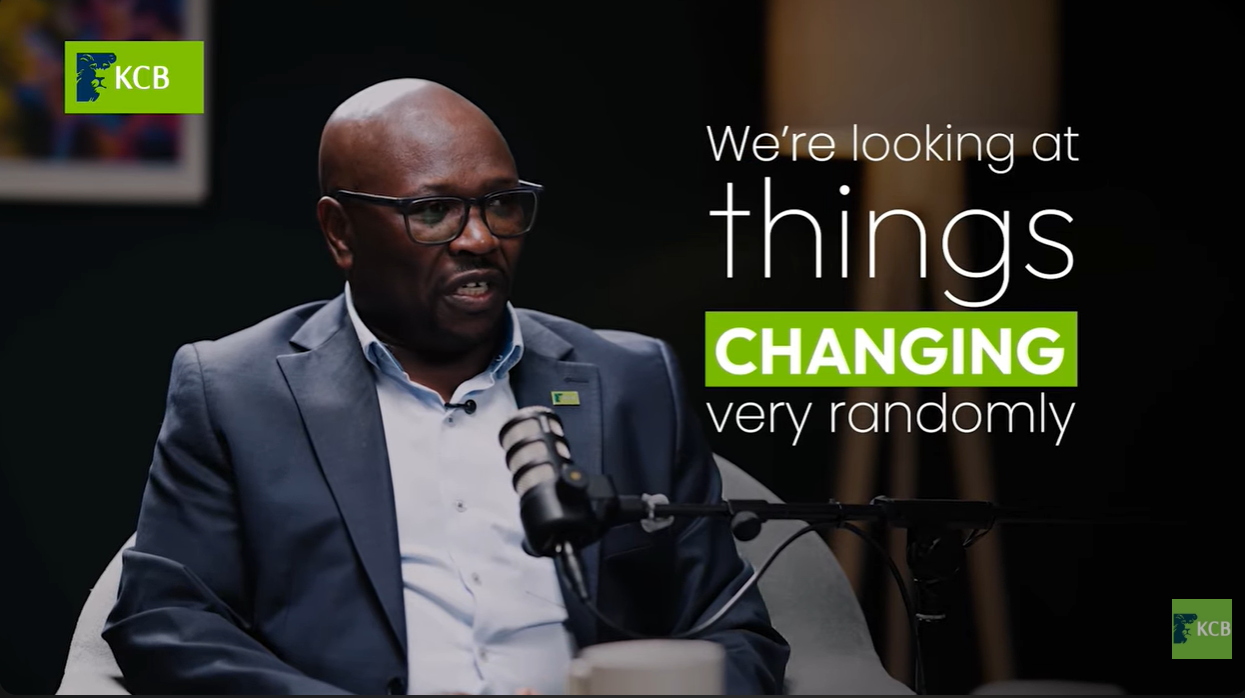
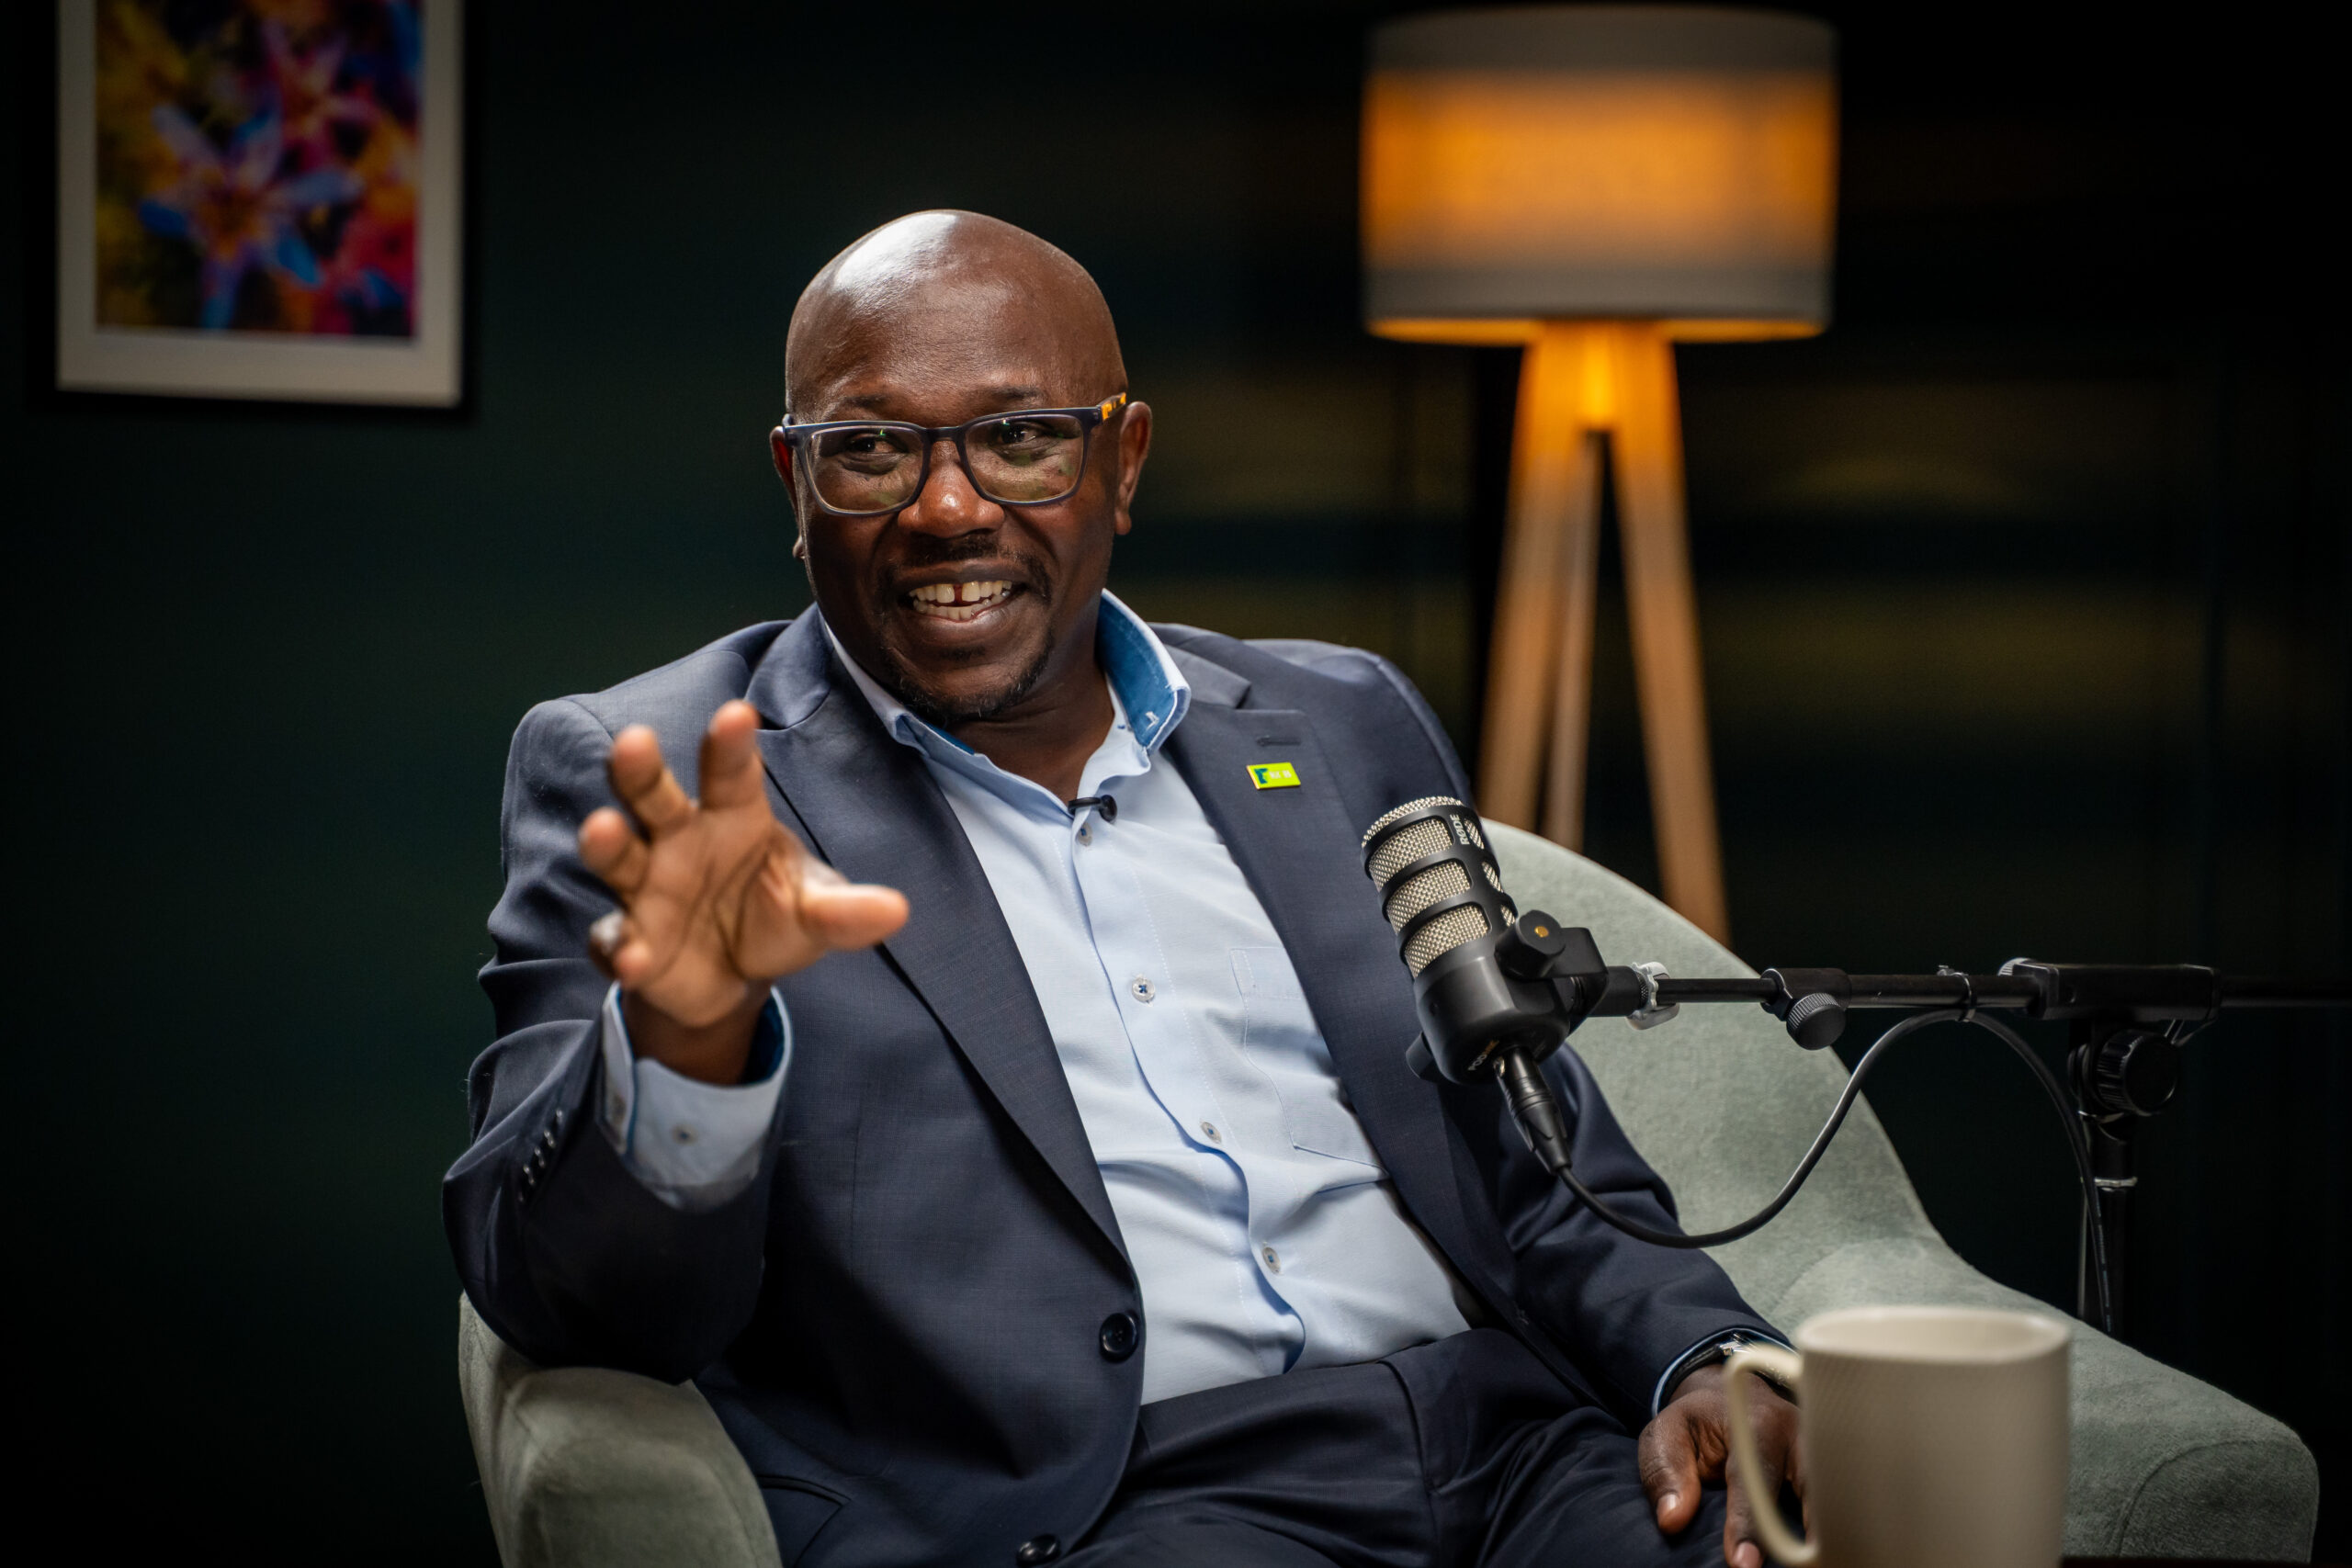
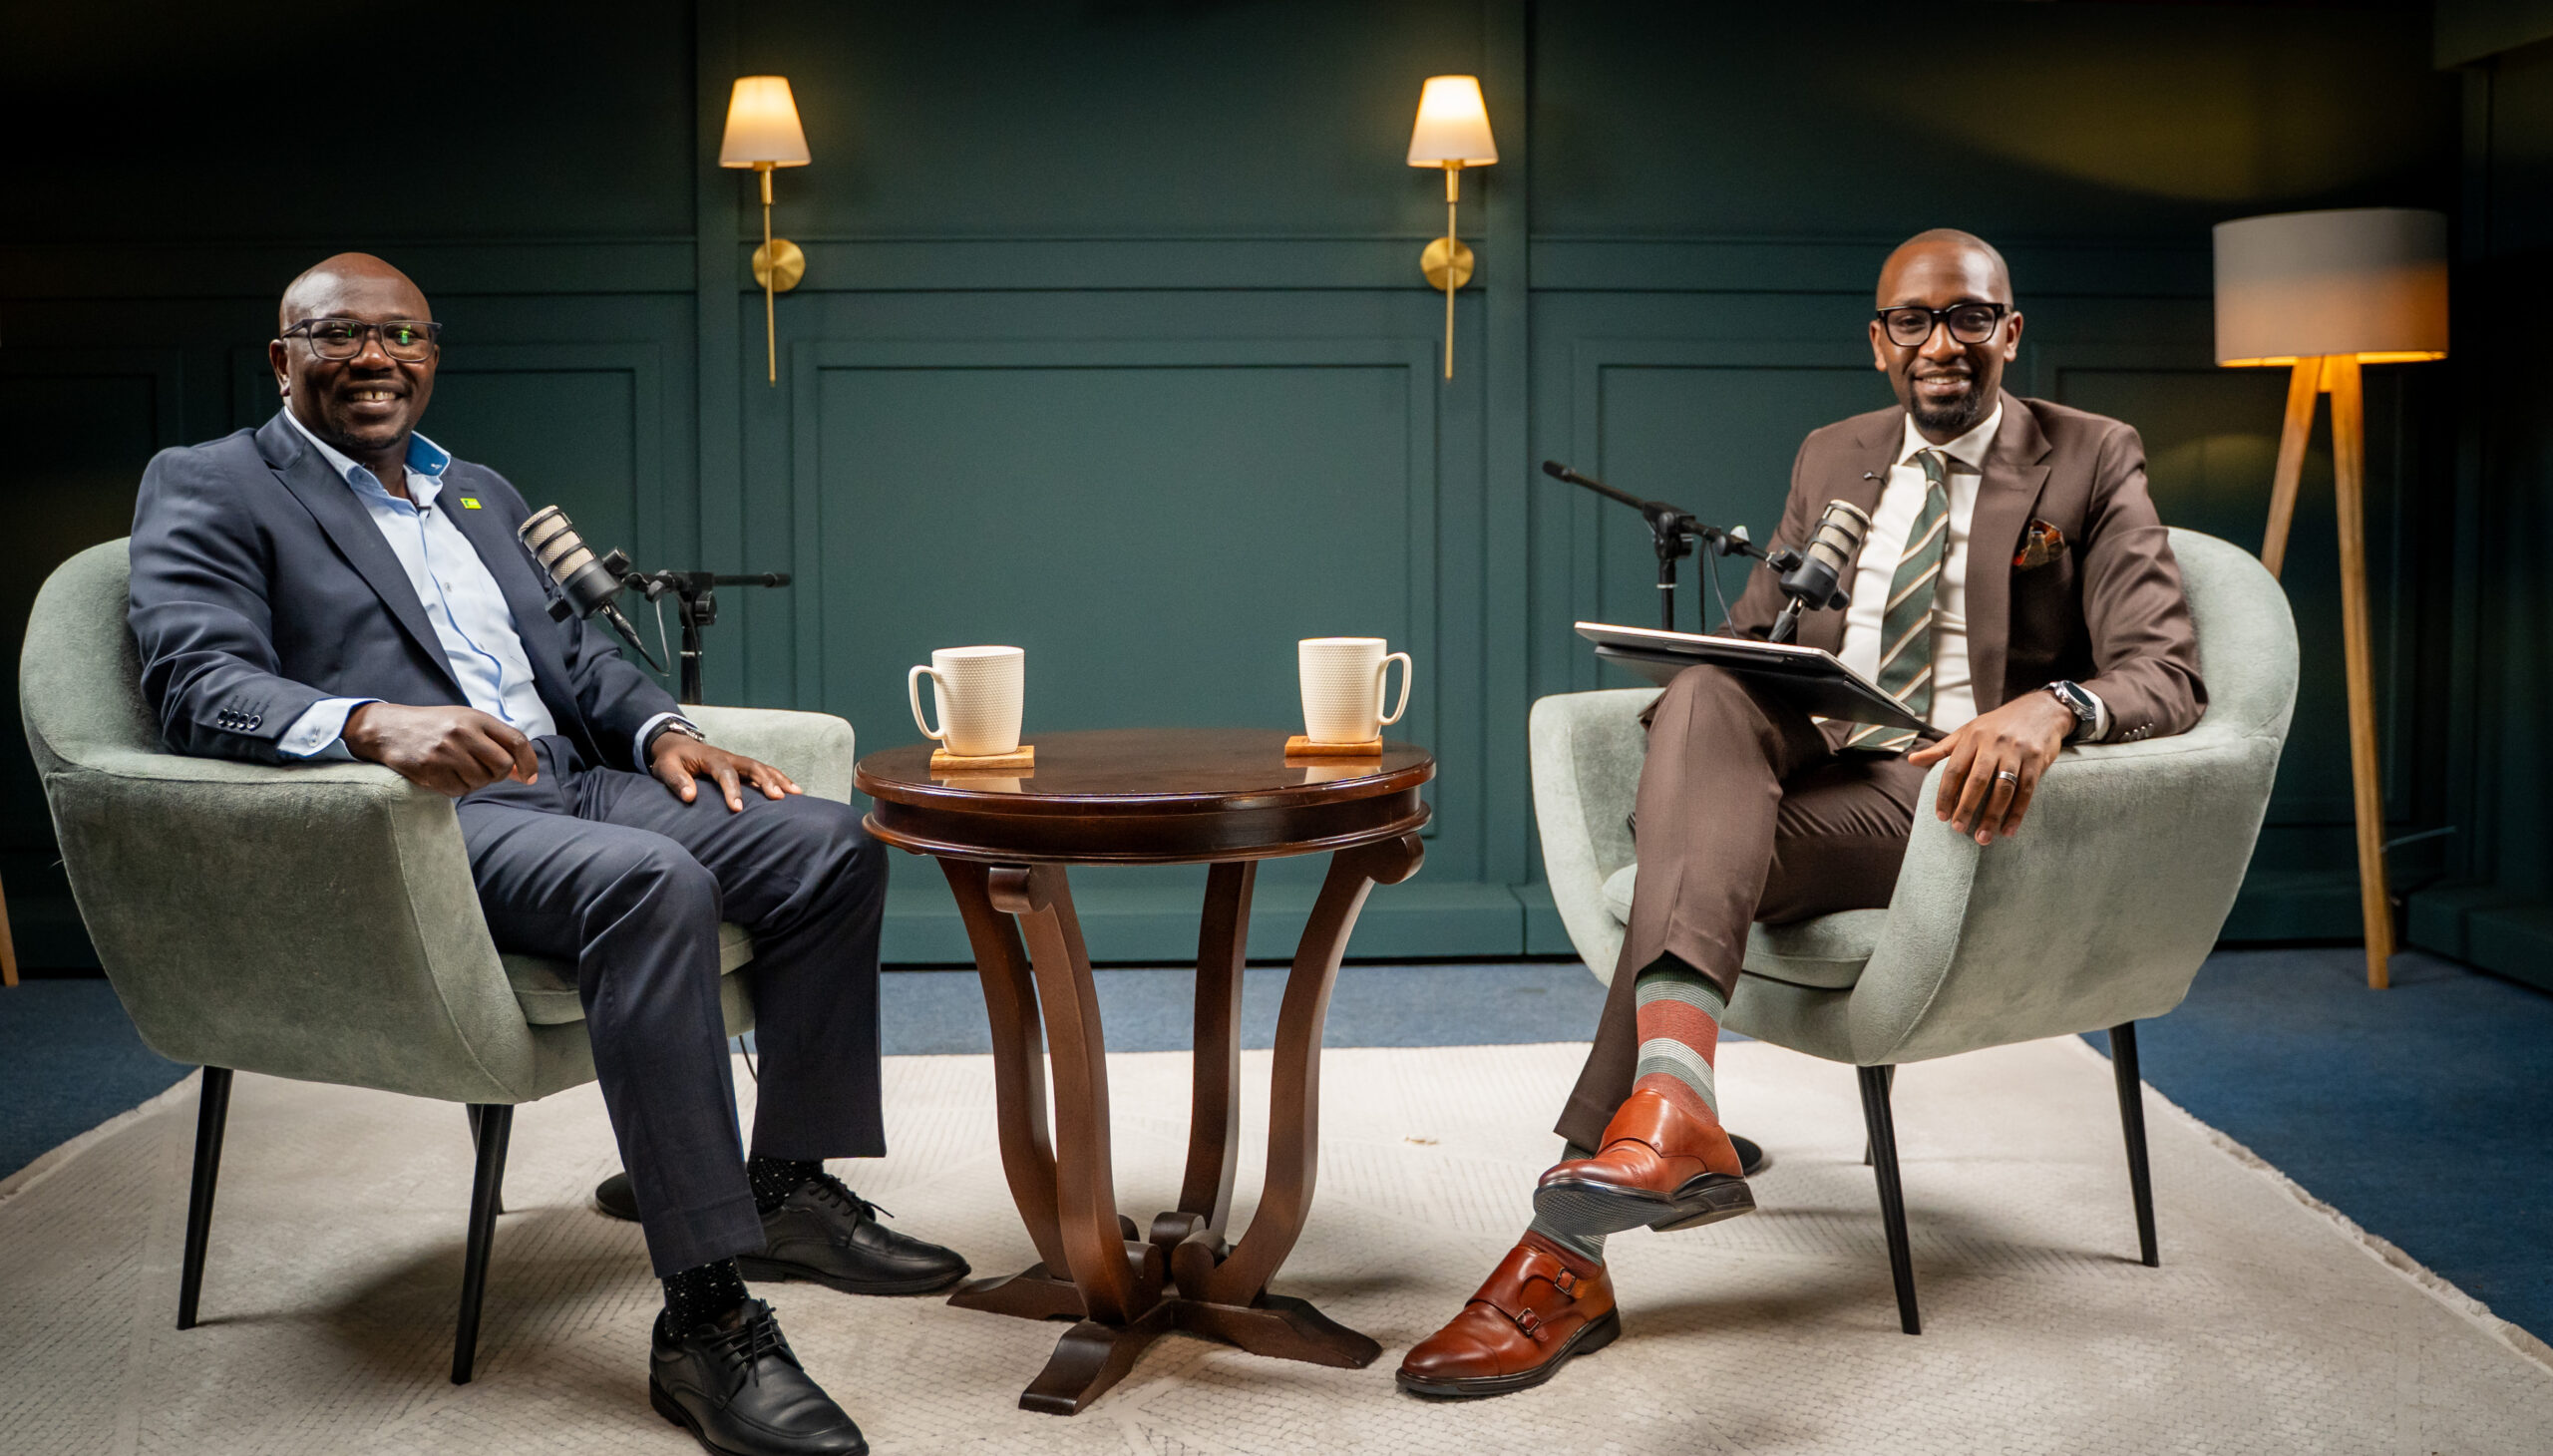
For Peter Njuguna, Director of the Treasury Division at KCB Bank Kenya, volatility and unpredictability are defining features of the current business environment.
“We are looking at things changing very randomly,” he says, pointing to geopolitical developments and energy price movements as examples of external events that can quickly influence business conditions.
His observation highlights an important distinction for business leaders: uncertainty itself is not always avoidable, but being unprepared for its financial consequences may be.
A business that understands its exposure to changing input costs, borrowing rates or currencies has a clearer basis for evaluating its options than one that responds only after margins have narrowed or cash flow has come under pressure.
This does not make forecasting redundant. It makes forecasting more useful when it incorporates alternative scenarios and identifies the conditions under which management may need to change course.
Read More: What It Takes to Unlock Opportunity in a Changing Global Economy
Translating the Indicators Into Business Decisions
Macroeconomic indicators become useful when businesses can connect them to financial outcomes.
The relevant question is not simply whether an indicator is rising or falling, but what that movement means for the company’s operations and financial position.
Inflation: The Effect Extends Beyond Input Prices
Inflation measures the rate at which the general level of prices rises over time. For a business, its effects can extend well beyond the immediate cost of raw materials or inventory.
Rising prices can increase expenditure on materials, transport, energy and wages. The extent to which businesses can pass these costs on depends on their pricing power, competition and customers’ ability to absorb increases.
A manufacturer operating on thin margins, for example, may face rising input costs while being unable to increase selling prices at the same pace.
A distributor may need more working capital to maintain the same volume of stock. In both cases, revenue growth can mask a deterioration in cash flow or profitability.
Inflation can also affect demand. As households and businesses contend with higher living and operating costs, discretionary spending may weaken, payment periods may lengthen, and customers may become more price-sensitive.
For finance teams, the task is to identify which costs are increasing, how quickly those changes are reaching the business, and whether pricing, procurement and working capital policies can absorb the impact.
Interest rates: The cost of money shapes the timing of decisions
Interest rates influence borrowing costs, investment returns and the opportunity cost of committing capital.
For a company with variable-rate debt, changes in lending rates can affect interest expenses and debt-service capacity. Businesses considering expansion must also evaluate whether the expected return on a project remains attractive under different financing assumptions.
The direction of monetary policy provides useful context, but it does not determine every company’s borrowing cost. Lending rates also reflect factors such as credit risk, loan structure, tenor and the terms agreed between a lender and borrower.
For businesses, a change in the central bank’s policy rate should therefore prompt an assessment of actual financing exposure rather than an automatic change in investment plans.
A company with fixed-rate borrowing may be affected differently from one whose interest payments change with market rates.
The decision is ultimately about affordability, the resilience of future cash flows and whether the expected returns justify the cost of capital.
Foreign exchange: Exposure is determined by the business model
Currency movements can affect a company’s earnings even when its operations are entirely domestic.
An importer paying suppliers in US dollars may face higher local-currency costs if the shilling weakens.
An exporter receiving foreign currency may benefit from the same movement when converting earnings into shillings, although that advantage can be offset by imported inputs, foreign-currency debt or other costs.
The net effect depends on the company’s underlying exposures, not simply on whether the currency is strengthening or weakening.
Peter notes that geopolitical developments and disruptions to energy markets are among the external factors Treasury monitors because they can influence foreign exchange and, in turn, customers’ businesses.
“We are looking at things changing very randomly.” Geopolitical developments and shifts in energy prices can quickly alter market conditions, with implications for foreign exchange and customers’ operating costs.”He said.
For finance leaders, this calls for a clear view of expected foreign-currency receipts and payments, their timing, and the extent to which they offset one another.
A company with dollar-denominated obligations due in three months has a different risk profile from one that receives dollar revenue over the same period.
Understanding that difference allows a business to assess whether it needs to align foreign-currency inflows and outflows, adjust payment timing or consider appropriate hedging arrangements.
Global Developments
Geopolitical tensions can affect energy prices, shipping costs and foreign exchange markets, with consequences for businesses far beyond the regions directly affected.
Peter describes the economy as a connected system involving businesses, commercial banks, global markets and central banks.
Within that system, central banks influence monetary conditions and support price stability, while market movements affect the financial decisions companies must make.
For businesses, the practical lesson is to trace a market development through to its likely operational and financial consequences.
Treasury teams help bridge the gap between market movements and business decisions by monitoring global markets, advising on interest and exchange rate trends, and working with clients to identify solutions that manage financial exposure.
For KCB, this means helping businesses assess risks and make informed financial decisions as conditions change.
Managing Risk Starts With Understanding Exposure
Monitoring market developments is necessary, but it does not, by itself, reduce risk. That requires a business to identify where it is exposed and decide how much volatility it can reasonably absorb.
A practical starting point is to identify key exposures, such as exchange rate changes, rising borrowing costs, more expensive imports and higher energy bills.
Understanding these risks can help guide decisions on pricing, purchasing, borrowing, cash reserves and investment.
Where exchange rate changes pose a significant risk, businesses can explore options such as forward exchange contracts to help manage potential losses.
The aim is not to eliminate every risk, but to understand which risks the business can absorb and which could threaten its financial position.
Cash flow is part of this: a business can be profitable but still struggle to meet its obligations if payments come due before money comes in.
Treasury Is Becoming a Strategic Business Partner
Traditionally, businesses may have viewed treasury primarily through the mechanics of payments, bank balances, borrowing and foreign exchange transactions. But as financial conditions become more interconnected, its potential contribution extends to strategic planning.
Treasury can help management interpret market information, quantify exposures, assess financing alternatives and understand how changes in interest rates or exchange rates might affect future cash flows.
Peter describes the function at KCB Bank Kenya as one that manages risk within the bank, monitors global markets and provides guidance on interest rates and exchange rates. He also emphasizes its role in supporting customers as they navigate those forces.
“We partner with our customers to offer solutions and support their businesses,” he says.
For a corporate finance team, the broader principle is that market intelligence should inform decisions before commitments are made, not only after a movement has affected results.
Treasury input can be relevant when negotiating supplier contracts, deciding whether to borrow in local or foreign currency, evaluating an export opportunity, planning a major import or determining how to manage a future payment obligation.
It is not a substitute for management judgement nor does it remove the need for independent analysis of a company’s operations and financial position. Its value lies in helping decision-makers connect market developments to specific exposures and available responses.
That makes the relationship between a business and its financial advisers more useful when it is grounded in the company’s actual cash flows, contractual obligations and commercial objectives, rather than a general view of where markets may be heading.
East Africa: Growth Opportunities Require the Same Market Discipline
Regional expansion can diversify revenue and open new markets, but it also brings additional costs and financial risks.
According to the East African Business Council’s East Africa Trade and Investment Climate Report 2026, total EAC trade reached US$156.6 billion in 2025, while trade among member states stood at US$19.54 billion, up 28.2% from the previous year.
Intra-regional trade accounted for about 12.5% of the total, with non-tariff barriers, inconsistent customs processes and limited access to finance among the constraints identified in the report.
For businesses considering expansion, the opportunity must be weighed against the cost of entering and operating in new markets.
Customer demand, competition, transport costs, regulatory requirements, currency movements and payment reliability can all affect profitability and cash flow.
The decision should therefore go beyond potential sales to consider the funding required to sustain operations, the time needed to collect payments and the expected return after financing and currency costs.
Turning Market Signals Into Business Decisions
Reading the markets is not about predicting every economic shift. It is about understanding which developments matter to a business and how they could affect costs, cash flow, financing and growth.
Inflation, interest rates, exchange rates and geopolitical developments can all influence business performance.
Understanding how these forces affect costs, cash flow and financing helps business leaders make better-informed decisions.
As Peter Njuguna notes, markets are not predictable. Businesses cannot control every external development, but they can strengthen their readiness by questioning assumptions, assessing risks and acting on the information available.
Ultimately, the advantage lies not in knowing exactly what the market will do next, but in understanding what changing conditions mean for the business and being prepared to respond.